Thrift Savings Plan

- 1.91K Reviews
- 4.8
- Downloads
- 500,000+
Our take on Thrift Savings Plan from Appgk
Managing a retirement account is rarely something I want to turn into a daily project. I want to see where things stand, make an informed change when necessary, and get back to my day without hunting through unrelated tools. Thrift Savings Plan is built for that focused job: it is a free Business app from FRTIB for people who use the Thrift Savings Plan and want account access from an Android or iOS device.
After spending time with it, I see the app less as a general personal-finance dashboard and more as a direct doorway into one specific retirement plan. That distinction matters. If your financial life revolves around the TSP, the narrow focus is useful. If you want one app to combine banking, credit cards, brokerage accounts, budgeting, and investments from several providers, this is not trying to be that.
The app is available to Everyone, has passed the half-million-install mark, and holds a 4.8 average from roughly 5,500 ratings and 1,900 written reviews. Those figures suggest that many users find the basic experience dependable, although popularity alone does not tell me whether it will match your particular workflow. The current version is 7.2.0, and it requires iOS or Android 12 or newer, so checking your device before installing is a sensible first step.
How I would decide whether it belongs on your phone
Start with the job you need it to do
The first question is not whether this is the most polished finance app you have ever used. It is whether you need a mobile way to deal with your TSP specifically. For that purpose, a dedicated app can be more practical than a broad money-management service that only shows a partial picture or relies on linked-account updates.
Best Parts of Thrift Savings Plan
Things to Keep in Mind About Thrift Savings Plan
I would consider it a strong candidate if you regularly check your retirement balance, review account activity, or need to make plan-related decisions while away from a computer. It is also useful for someone who wants a clear separation between everyday spending and long-term retirement savings. Keeping those two tasks in different places can reduce the temptation to treat retirement money like a checking-account balance.
On the other hand, I would not install it expecting a complete financial command center. Its value comes from direct attention to the Thrift Savings Plan, not from replacing every other money tool. A person with several investment accounts may still prefer a consolidated portfolio app for an overall view, while using this one whenever TSP-specific access matters.
News and Features Related to Thrift Savings Plan

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The small details that affect the decision
Cost is easy here: the app is free. That removes one common barrier, but it does not remove the need to think about security and access habits. A retirement account deserves more care than a casual shopping or entertainment app. I would install it only on a device I keep updated, use a screen lock on, and avoid checking sensitive account information over an unsecured public connection.
The operating-system requirement is another practical filter. If your phone cannot run Android or iOS 12, this app is not a good fit for that device. I would not treat that as a minor technical footnote, because an unsupported phone can leave you choosing between an inconvenient browser session and replacing or updating the device.
Don't want to read the full review?
I also pay attention to the developer in a finance app. Here, the developer is FRTIB, which gives the product a direct connection to the organization behind the plan rather than making it a third-party viewer. That does not mean every user will love every screen, but it does make the app’s purpose easier to understand: it is intended for TSP account access, not for selling a separate financial service.
A realistic everyday use case
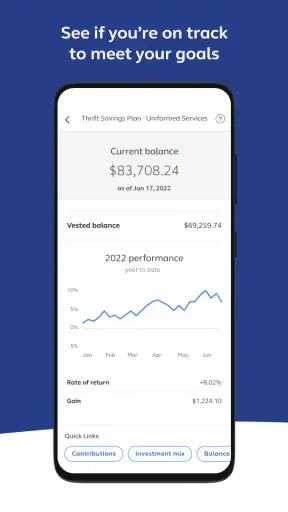
Imagine checking your retirement account during a lunch break after receiving a work-related reminder to review your savings choices. I would open the app, sign in, look at the current account picture, and review the relevant information before deciding whether any action is actually needed. The useful part is the short path from concern to verification: instead of relying on an old statement or a third-party estimate, I can look at the account itself.
Screenshots
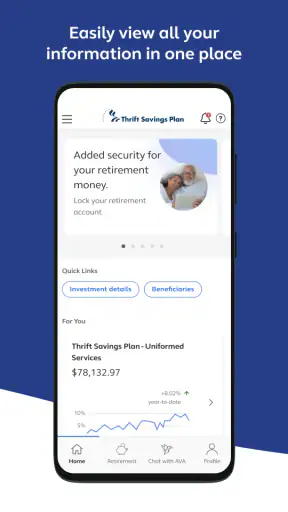
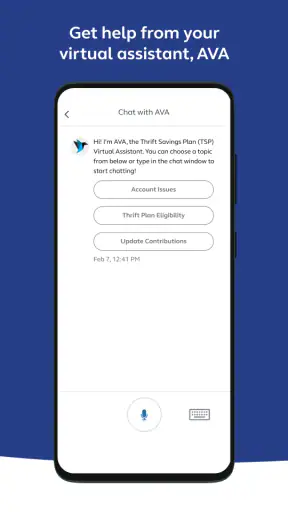
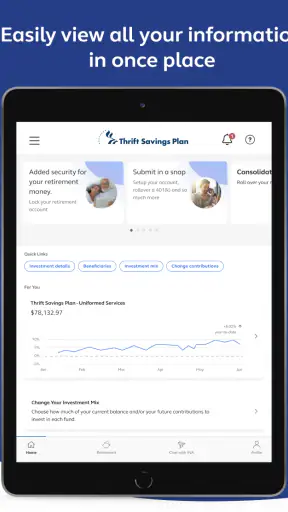
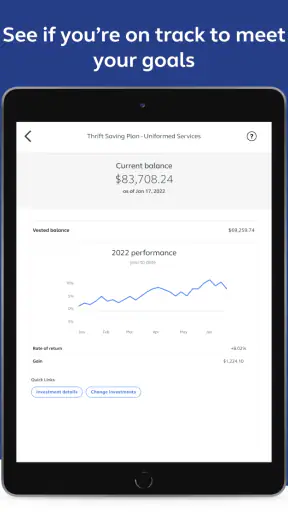
That workflow also encourages a healthier habit. I would avoid making a change simply because the market or my balance looked different on one particular day. The app is most helpful as a place to confirm facts and carry out a considered decision, not as an invitation to constantly react. Checking first, writing down what I intend to review, and then closing the app is a better routine than repeatedly refreshing it.
Where the dedicated TSP approach works best
It keeps retirement access focused
My favorite quality is the lack of distraction created by its narrow purpose. A general finance app often puts spending charts, credit offers, cash-flow alerts, and multiple investment accounts on the same screen. That can be helpful for budgeting, but it can also bury the one account I opened the app to inspect. Thrift Savings Plan keeps the decision centered on the retirement plan itself.
That focus is especially helpful when you are reviewing a contribution or allocation decision. I can approach the task with one question in mind rather than sorting through unrelated balances. For users who prefer a clean boundary between retirement planning and household budgeting, this is a meaningful advantage over an all-in-one financial dashboard.
It is better suited to direct account work than a portfolio aggregator
Portfolio aggregators are convenient when the goal is to see many institutions together. Their weakness is that the information may be presented as a summary rather than as the primary account experience. A dedicated TSP app makes more sense when I need to work with the TSP itself instead of merely adding its balance to a larger net-worth chart.
This distinction becomes important when an account connection is delayed or a linked service displays an old figure. I would rather use the dedicated app to verify the current position before making a retirement decision. The trade-off is that I must open another app for other investments, but the information is organized around the account that matters at that moment.
It supports a deliberate review routine
One less obvious benefit of a specialized account app is that it can make review sessions easier to control. I would use it at a planned interval, note the information I need, and leave broader financial planning to a separate session. That reduces the risk of mixing a long-term retirement choice with an impulsive reaction to a short-term spending problem.
For example, I might use a budgeting app to decide how much I can save, then use this app to inspect the TSP side of that decision. Those are different questions. Separating them helps me avoid confusing “Can my monthly budget support this?” with “How should my retirement account be managed?” The app does not need to answer both questions to be useful.
The audience is broad, but the purpose is specific
The Everyone age classification makes the app approachable from a store perspective, yet the practical audience is narrower: people who have a reason to access a TSP account. A new participant may appreciate having a mobile entry point instead of depending entirely on paper records or a desktop browser. An experienced participant may value the convenience of checking the account while traveling or between work tasks.
I would still encourage new users to learn the meaning of any TSP terms before acting. A convenient interface can show account information, but it cannot replace understanding the consequences of a retirement decision. The app works best when it supports your knowledge rather than pretending to be a substitute for it.
What I would do before trusting it with a routine
My first session would be deliberately cautious. I would confirm that I installed the official app, sign in without saving sensitive details in an unsafe place, and inspect the account information before trying any action. I would also make sure I understand how to leave the session securely, especially if I am using a shared or borrowed device.
After that, I would create a simple personal checklist: open the app only when I have a clear reason, verify the account information I need, record any decision outside the app if it requires later reflection, and sign out or lock the device when finished. This is not glamorous advice, but it is more useful than treating a retirement app like a casual news feed.
Where another type of tool may fit better
Choose a broader finance app for a whole-money view
If your main question is “How are all my accounts doing together?”, a consolidated finance app may be the better first stop. It can give you a wider household view across banking, cards, investments, and spending, while this app remains focused on the TSP. I would not force one tool to perform both jobs when the broader view is what I actually need.
The compromise is that a broad service may not offer the same direct TSP-centered workflow. It may be excellent for trends and budgeting but less suitable when I want to verify account-specific information or handle a TSP task. In that situation, I would use both categories rather than choosing one permanently: the aggregator for context and this app for the TSP account itself.
Use a brokerage app when your investments live elsewhere
Someone whose primary investments are held with a brokerage may prefer that brokerage’s app for research, trading, and portfolio management. Thrift Savings Plan is not the natural choice for those activities because its purpose is tied to the TSP. Installing it will not make a separate brokerage account part of the same experience.
This is one of the clearest cases where a different option is better. If you are comparing securities across a brokerage account and need tools built around that account, use the platform that actually holds those investments. Keep this app for the TSP-related information rather than expecting it to become a universal investment terminal.
A browser may still be preferable in some situations
There are times when I prefer a larger screen, especially when I am comparing documents, reviewing a complicated decision, or working through several pieces of financial information at once. A mobile app is convenient, but convenience is not the same as suitability for every task. If a decision requires careful reading, I would choose the interface that lets me concentrate and verify details comfortably.
The app is most convincing for quick access and routine account checks. It is less compelling as the sole place for every retirement-planning activity. That is not a flaw so much as a reminder to match the tool to the job: phone access for timely verification, a larger screen or other resources for deeper planning.
Who should probably skip it
I would skip it if I do not participate in the TSP, if I am looking for a general budgeting app, or if my phone cannot meet the minimum operating-system requirement. I would also think twice if I rarely use mobile finance tools and already have a desktop routine that serves me well. Installing another app adds little value when it does not solve a real access problem.
I would not recommend relying on it as a financial adviser. The app can be part of a decision process, but the decision still needs to reflect your situation, time horizon, and understanding of the plan. Anyone hoping for personalized guidance across their entire financial life should look for a service designed for that broader purpose.
Switching to a dedicated app without creating extra friction
Keep your existing method during the transition
Moving from a browser, paper statements, or another finance app does not need to be an all-or-nothing change. I would keep the old method available for a short period, install this app, and compare the account information I see rather than assuming the transition is complete immediately. That gives me a way to catch login problems or unfamiliar screens before I need urgent access.
I would also avoid changing account settings simply because the mobile interface is new. First learn where the information is displayed and how the sign-in process feels. Only after that would I decide whether the app is convenient enough to become my regular access point. This separates the question “Can I use it comfortably?” from the much more important question “Should I make a retirement change?”
Prepare for the security trade-off
Mobile access saves time, but it places account access on a device that can be lost, shared, or exposed to unsafe networks. My practical approach would be to protect the phone with a strong lock, keep the operating system current, and avoid leaving the account open after finishing. I would never treat free access as a reason to be careless with credentials or account screens.
There is also a convenience trade-off. The faster it is to open an account, the easier it can become to check compulsively or act without enough reflection. I would turn the app into a scheduled tool rather than a constant source of reassurance. That makes its convenience work for me instead of encouraging short-term reactions.
Use a two-tool workflow when your finances are more complicated
For someone with several accounts, switching completely to this app may be the wrong goal. I would use a broad finance tool to organize the household picture, then open the TSP app when I need the dedicated account view. This arrangement avoids the common mistake of judging an app harshly because it does not perform a job it was never meant to perform.
A useful workflow is to review the household budget first, identify whether there is a genuine retirement question, and then use the TSP app for account-specific verification. That order prevents a balance screen from becoming the starting point for an emotional decision. It also makes it easier to record what you checked and why, which is valuable when you revisit the issue later.
What the strong ratings do and do not tell me
The 4.8 average and substantial review activity give me confidence that the app has found an audience and that many people are satisfied with its everyday purpose. I see that as a positive signal for a dedicated account-access tool. Still, ratings cannot tell me whether the navigation feels natural on my particular phone, whether my preferred workflow is supported, or whether I will enjoy using a focused app instead of a broader financial dashboard.
That is why I would judge it after a few realistic sessions rather than after one quick launch. Can I find the information I need without confusion? Does it fit the moments when I actually manage my TSP? Does it reduce friction compared with my current method? Those answers matter more to me than a high number displayed in an app store.
My recommendation for TSP participants
I recommend Thrift Savings Plan to people who want direct, mobile access to their TSP and are comfortable keeping broader financial tasks in separate tools. Its strongest quality is focus. It is free, maintained by FRTIB, available to Everyone, and designed around a specific retirement account rather than a crowded collection of money features.
I would choose it over a generic finance app when my priority is checking or managing the TSP itself. I would choose a broader aggregator when my priority is seeing my entire financial life in one place. I would choose a brokerage app when my main activity concerns investments held with a brokerage. Those choices are not contradictions; they reflect different jobs.
The main limitation is also the reason to install it: it is specialized. That specialization means less clutter for TSP users, but it also means I should not expect budgeting, multi-provider portfolio management, or personalized financial planning from it. Users who understand that boundary are more likely to find the app useful and less likely to feel disappointed by what it does not attempt to be.
My final advice is to treat it as a practical access point, not as a replacement for thoughtful retirement planning. Install it if mobile TSP access would genuinely make your routine easier, confirm that your device meets the Android or iOS 12 requirement, and build a calm review habit around it. The best reason to use this app is simple: it puts the TSP task in the right place without pretending to manage every part of your financial life.
Thrift Savings Plan FAQ
What is the Thrift Savings Plan app used for?
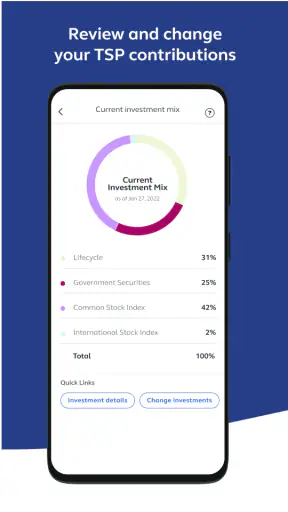
The Thrift Savings Plan app is designed to help eligible federal employees, members of the uniformed services, and other TSP participants manage their retirement savings more conveniently. After signing in, users can generally review account balances, monitor investment allocations, check contributions, view transaction information, and access plan resources without needing to use a desktop browser for every task.
Who can use the Thrift Savings Plan app?
Access is intended for people who already have an eligible Thrift Savings Plan account, including qualifying federal civilian employees, uniformed service members, and certain other participants. The app is not a general investment platform for opening an unrelated brokerage account. Eligibility, available features, and account access depend on your TSP status and the information associated with your official account.
Is the Thrift Savings Plan app safe to use?
The official app is intended to provide secure access to sensitive retirement-account information, using sign-in and identity-verification measures appropriate for financial services. Users should download it only from an official app store, confirm the publisher, keep the operating system updated, and avoid entering credentials through links received in suspicious messages. Never share passwords, verification codes, or security answers with anyone.
Can I change investments or manage contributions through the app?
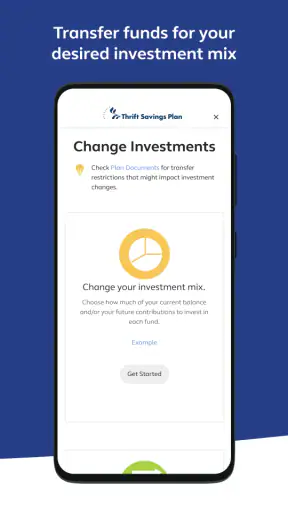
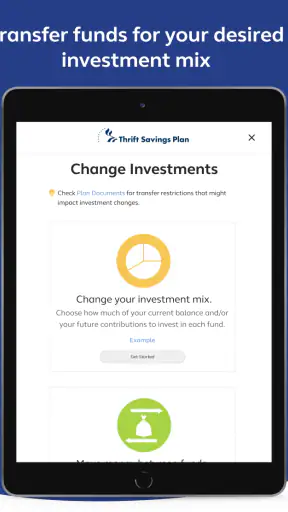
Depending on your account type and the features currently supported, the app may allow you to review contribution details, update investment allocations, or request certain account transactions. Retirement-plan actions can have long-term financial and tax consequences, so review all confirmation screens carefully before submitting a request. If an option is unavailable in the app, use the official TSP website or contact participant support.
What should I do if I cannot sign in or the app is not working?
First, check that you installed the official application, have a reliable internet connection, and are using the latest version available for your device. Re-enter your credentials carefully and follow the approved account-recovery or identity-verification process if necessary. Avoid repeatedly guessing passwords. If problems continue, consult the official TSP help resources or contact support through verified channels rather than relying on unofficial websites or social-media advice.